
Life Style
How to Prepare an Inheritance Plan That Protects Future Generations

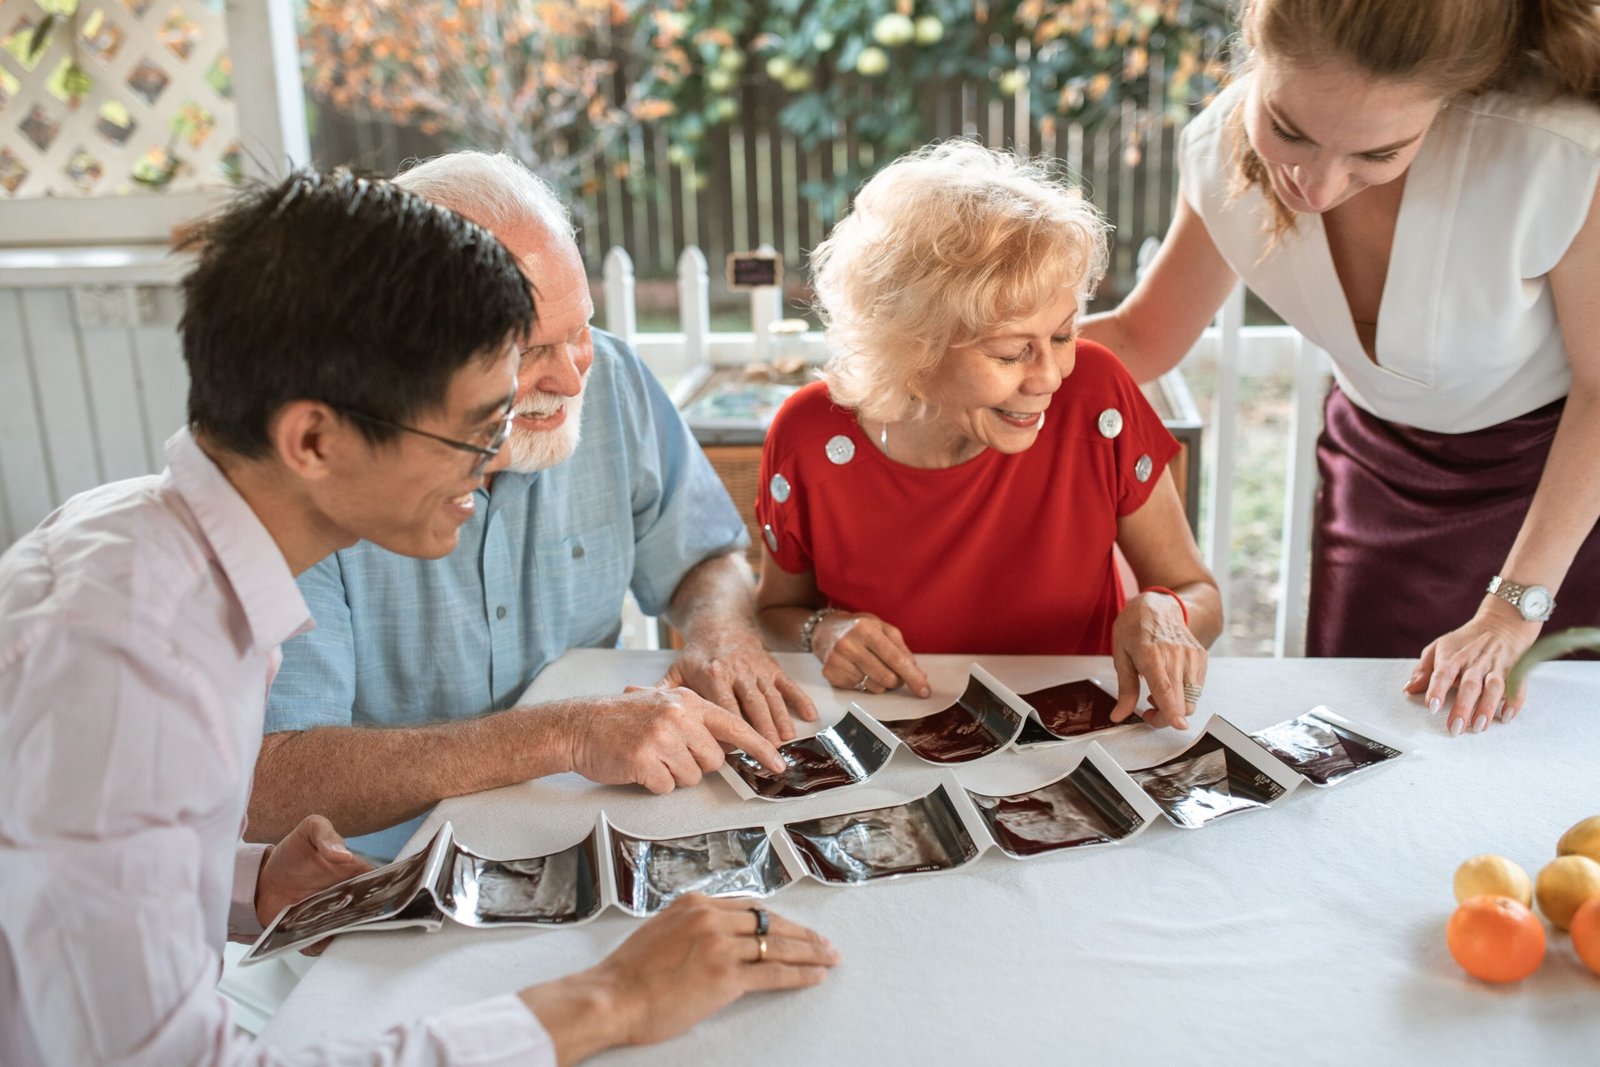
Leaving something meaningful behind for the people you love is one of the most thoughtful gifts you can offer. An inheritance plan is far more than a will or a simple list of assets. It is a carefully constructed strategy that reflects your values, your intentions, and your genuine commitment to your family’s well-being long after you are gone. Getting started can feel daunting, but breaking the process into clear, manageable steps makes it far more approachable than most people expect.
Start With a Clear Picture of Your Assets
Before you can plan how to distribute anything, you need a thorough understanding of what you actually have. This includes real estate, investment accounts, retirement funds, life insurance policies, business interests, and personal property. Many people are genuinely surprised to discover just how much their estate is worth once everything is tallied up. Organizing this information in one place gives you a solid foundation to build from and helps the professionals you work with provide the most accurate guidance possible. Clarity at this stage sets the tone for everything that follows.
Choose the Right Legal Structures
A basic will is a reasonable starting point, but it may not be enough to fully protect your family’s future. Trusts, for example, allow you to set specific conditions on how and when beneficiaries receive their inheritance, giving you considerably more control over the outcome. A revocable living trust can help your estate avoid probate, which saves your heirs both time and unnecessary legal costs. Depending on your situation, you might also consider irrevocable trusts, special needs trusts, or charitable remainder trusts. Working with an estate planning attorney ensures the structures you put in place actually align with your long-term goals.
Name Beneficiaries Carefully and Keep Them Updated
One of the most commonly overlooked aspects of estate planning is beneficiary designation. Designations on retirement accounts and life insurance policies often override what is written in a will, meaning outdated information can create serious, avoidable problems. If you named an ex-spouse as a beneficiary years ago and never updated it, that person could legally receive the funds regardless of your current wishes. Reviewing your beneficiary designations annually, or after any major life event like a marriage, divorce, or the birth of a child, keeps your plan current and accurate. This simple habit can prevent significant conflict and confusion down the road.
Have Open Conversations With Your Family
Many families avoid discussing estate plans because the topic feels uncomfortable, but transparency now can save enormous heartache later. When beneficiaries understand your intentions ahead of time, they are far less likely to feel blindsided or resentful after you are gone. These conversations do not need to be formal or heavy. A relaxed dinner table discussion can naturally open the door to important questions about values, expectations, and family dynamics. Letting your loved ones know where your documents are stored and who your advisors are is also a practical step that can make a genuinely difficult time much easier for everyone involved.
Factor In Tax Implications
Taxes can take a significant bite out of an estate when proper planning has not been done. Federal estate taxes, state inheritance taxes, and capital gains taxes can all affect what your heirs actually receive in the end. Strategies like gifting assets during your lifetime, funding 529 education accounts for grandchildren, or placing assets in tax-advantaged trusts can help reduce the overall burden considerably. A financial advisor with estate planning experience can walk you through the options that make the most sense for your specific financial picture. Planning proactively is almost always more effective than scrambling to minimize taxes after the fact.
Revisit and Revise Your Plan Regularly
An inheritance plan is not something you create once and file away forever. Tax laws change, family circumstances evolve, and your own financial situation will naturally shift over time. Most estate planning professionals recommend reviewing your plan every three to five years, or sooner if something significant changes in your life. Keeping your plan updated ensures it continues to reflect your current wishes and remains legally sound. Treating your estate plan as a living document, rather than a one-time task, is what truly separates a thoughtful, protective plan from one that falls short when it matters most.
Conclusion
Building an inheritance plan that protects future generations takes time, intention, and the right professional support. When you approach it with genuine care, you give your loved ones far more than financial assets. You give them clarity, security, and a lasting reflection of what mattered most to you throughout your life.

How to Prepare an Inheritance Plan That Protects Future Generations
Scratch Cards Online All Casino Games Uk
Deposit 25 Get Free Spins Online Blackjack Uk

Clint Eastwood Net Worth and Family Life: What You Didn’t Know

Best X Video Downloader Without Watermark — How to Get Clean HD Files

Inside Richard Hammond’s Life: How He Built His Net Worth
-
 Celebrity12 months ago
Clint Eastwood Net Worth and Family Life: What You Didn’t Know
-
 Technology5 months ago
Best X Video Downloader Without Watermark — How to Get Clean HD Files
-
 Celebrity11 months ago
Inside Richard Hammond’s Life: How He Built His Net Worth
-

 Celebrity11 months ago
Mark Normand net worth revealed: his career, lifestyle, and more